

It’s typically not difficult to identify trends when it comes to investing.
Think of some of the historical trends over the past couple of centuries:
1848 California Gold Rush
The 2nd Industrial Revolution around 1900
The Internet Boom in the 1990s
The AI Rush Right Now
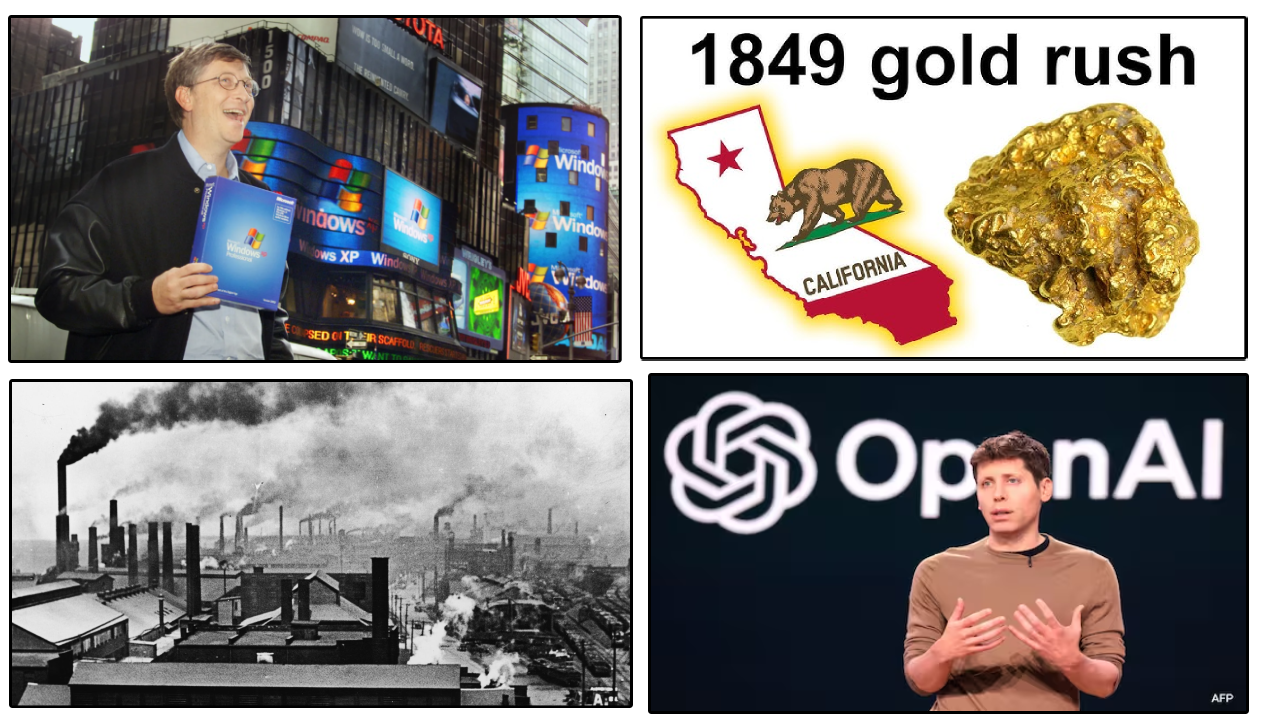
Investors have historically been quite good at realizing the impact these trends would have on the economy and stock market in general.
However, they’ve been incredibly bad at capitalizing on these trends.
Most people who moved to California in hopes of striking gold found nothing
Most who invested during the internet boom were wiped out during the dot com bubble
Only a small group of people truly capitalized from the Industrial Revolution
But there’s another opportunity that is about to take place right before our eyes…
📊 The REIT Trend
Did you know we are currently in the midst of a REIT trend?
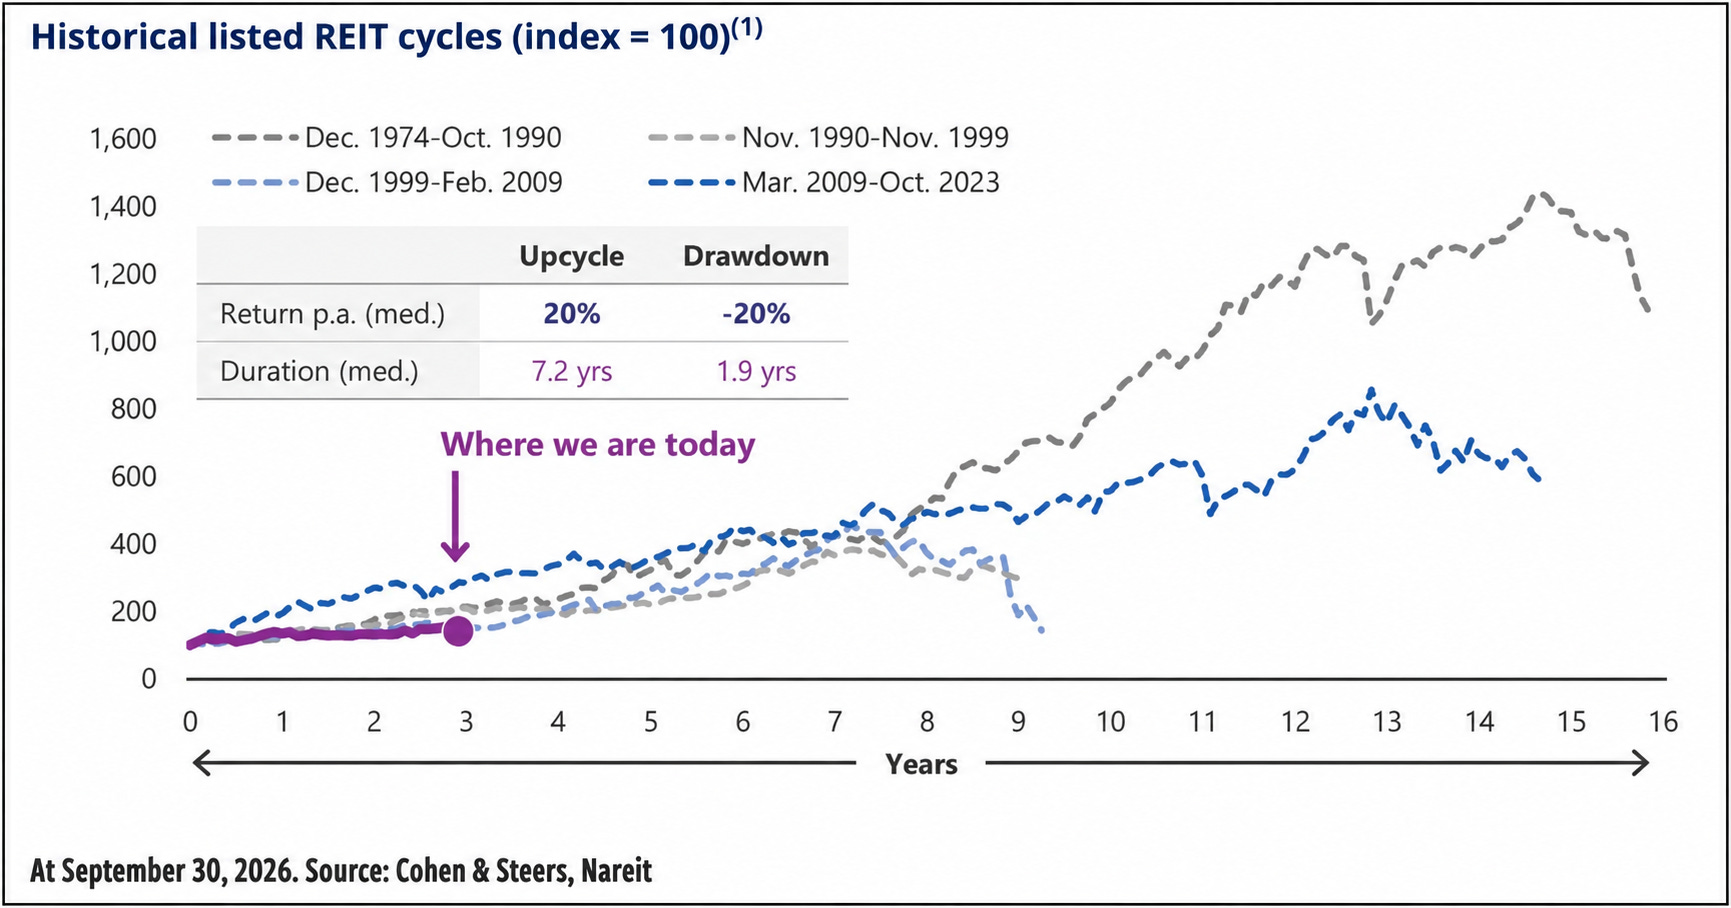
Cohen & Steers tracks four previous REIT cycles.
Across those cycles, the median upcycle lasted 7.2 years and delivered a 20% annualized return. (Wow!)
As of September 30, 2026, the current recovery was about three years in and had gained less than three of those four cycles did at the same point.
That gives us a bit of historical context for how much room this recovery could have.
But where does this put their valuation?
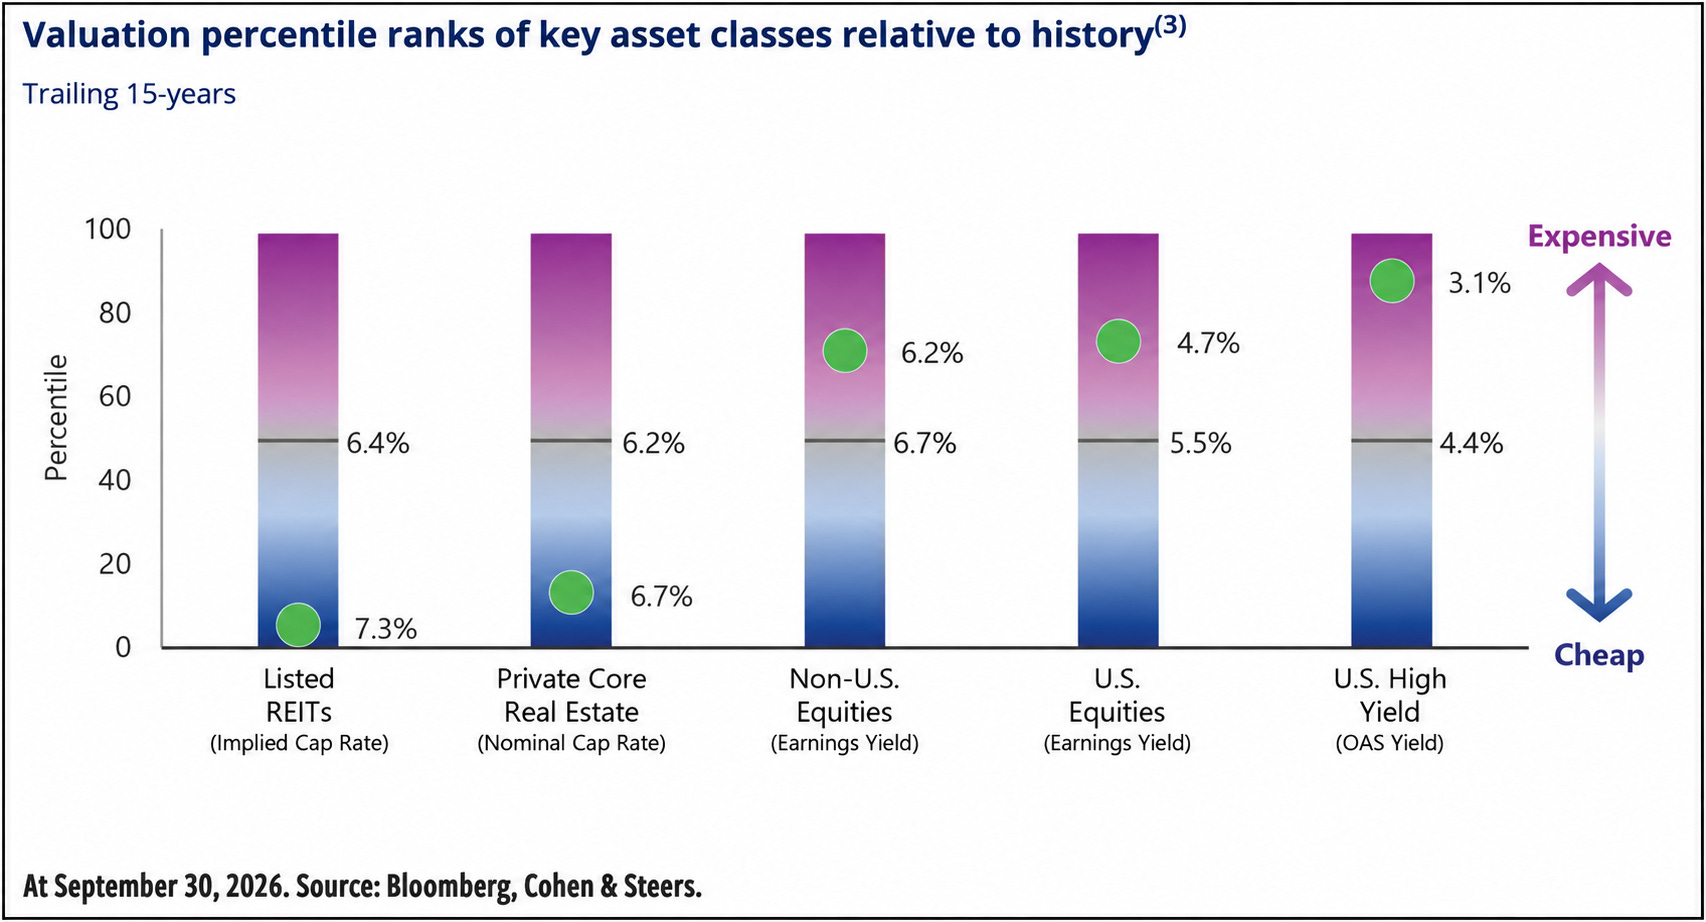
Listed REITs had a 7.3% implied cap rate, versus a 6.4% historical median.
To put this as simply as possible-
Investors were paying less per dollar of property operating income than they typically have over the past 15 years.
That put REITs near just the 5th percentile of their own valuation history, meanwhile U.S. equities were around the 75th percentile of theirs.
So how do we take advantage of this?
🏢 Creating a REIT Investable Universe
The idea of creating an ‘Investable Universe’ makes it incredibly easy to identify opportunities.
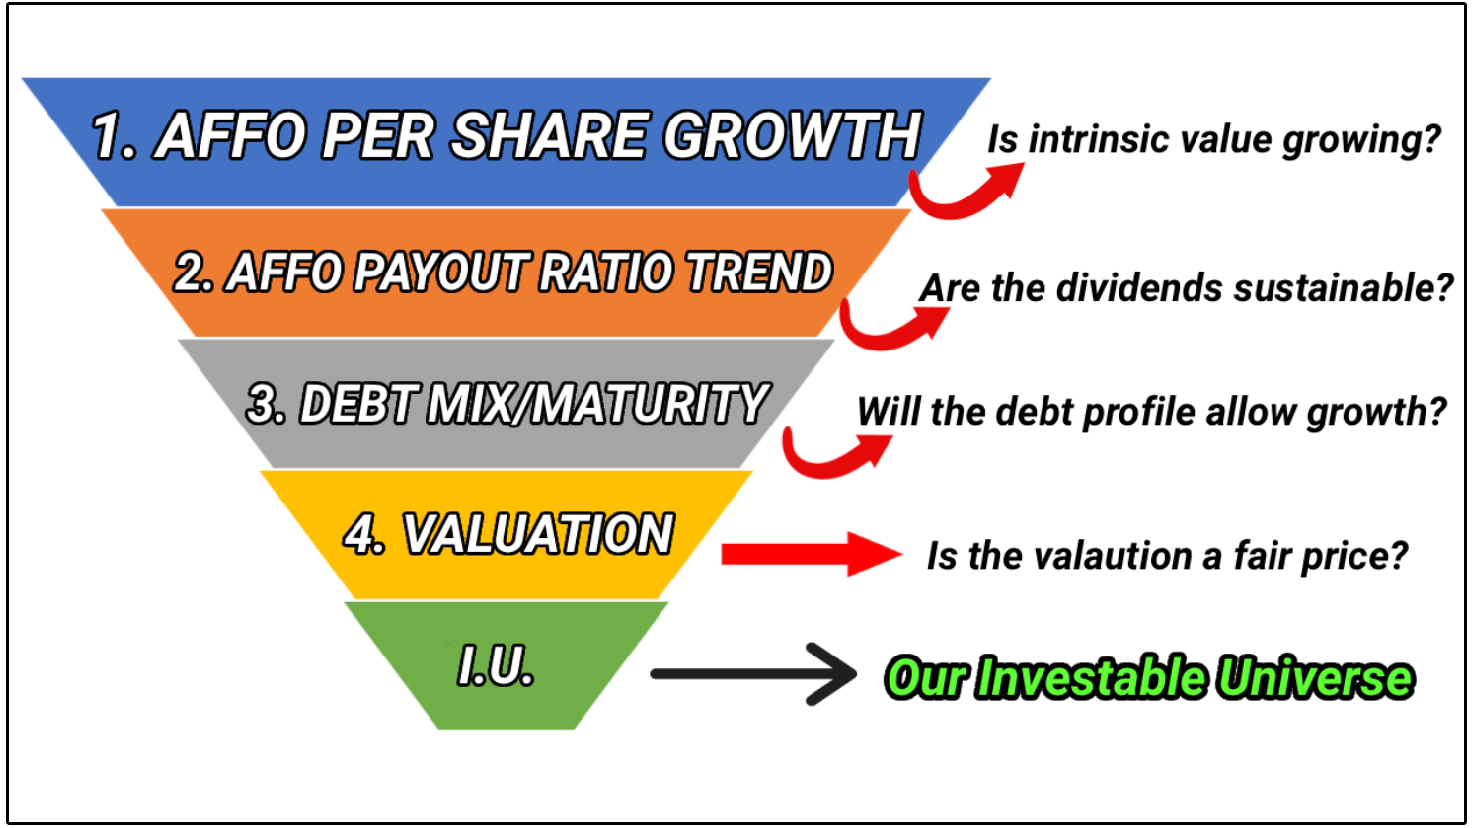
An investable universe is simply the full set of assets you’re willing and able to invest in based on your strategy, rules, or constraints.
For example, there are plenty of bad REITs out there.
To take advantage of REITs trading at a discount, we need to filter out the bad ones from the ones with potential.
To do this, we will turn to the Dividendology REIT Database.
📌 Dividendology REIT Database
The Dividendology Database is available for members of Dividendology.
But today, I’m sharing a portion of it with everyone.
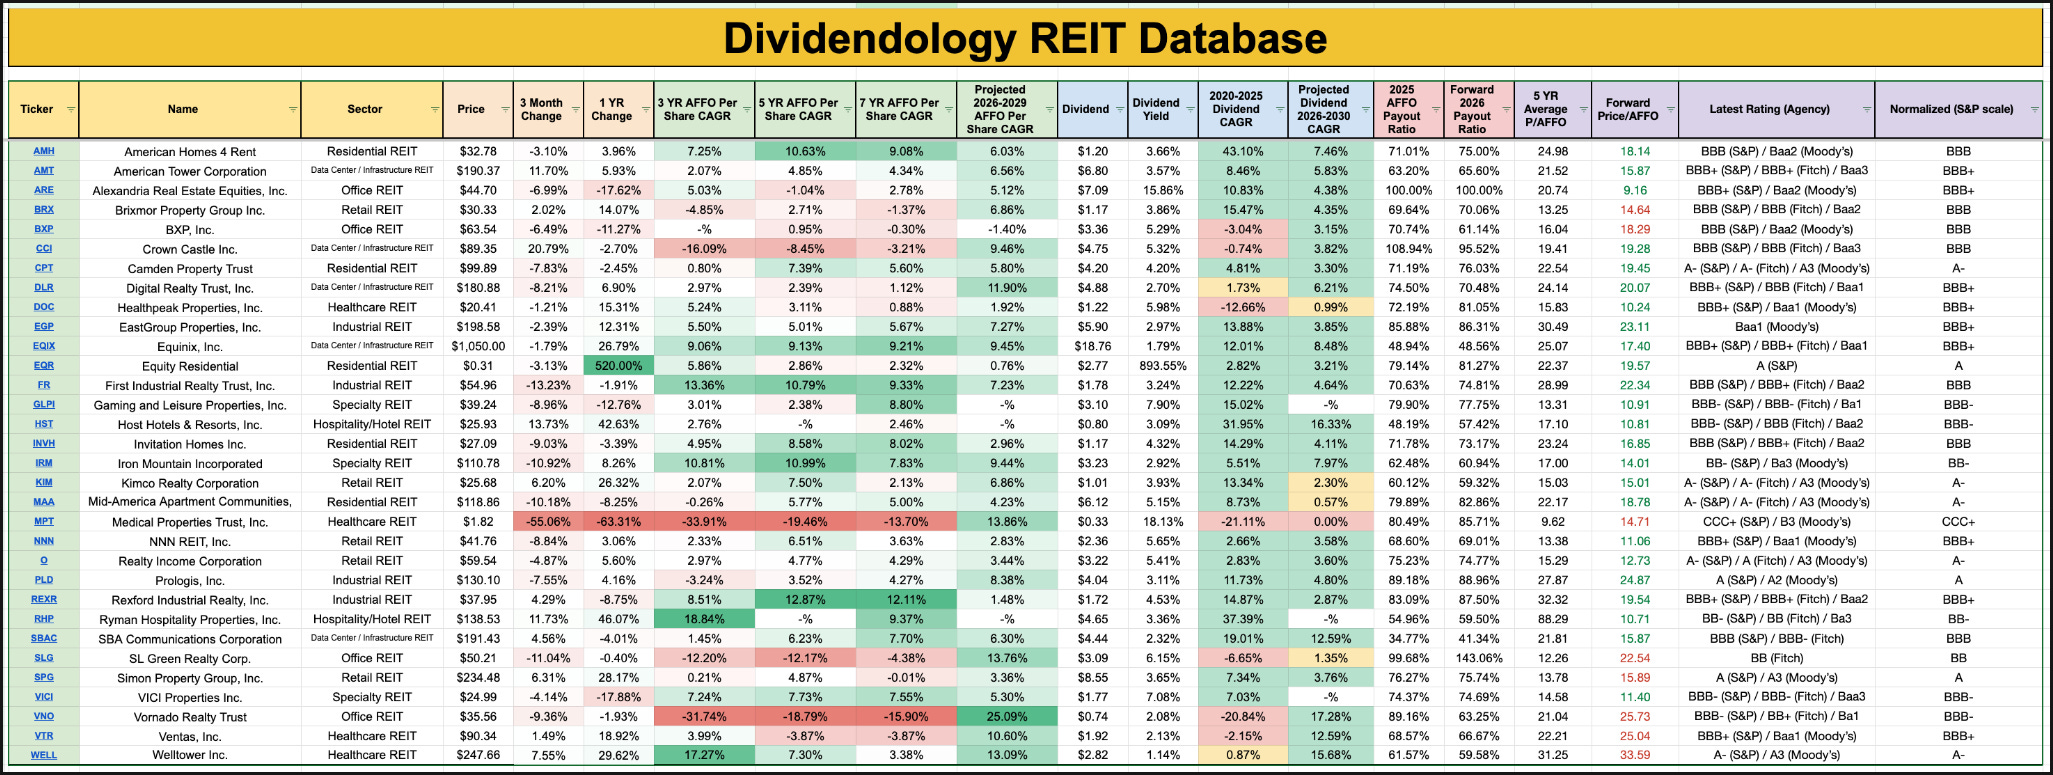
There are currently 33 REITs being tracked in the REIT Database.
Let’s see if we can use our investable universe screen to narrow this down.
We want to look for REITs that are fundamentally strong, so to start, we look for AFFO per share growth.
🗂️ 1. Growing AFFO Per Share
When we want to see if a stock is growing intrinsic value, we see if they are growing free cash flow.
When we want to see if a BDC is growing intrinsic value, we see if they are growing tangible book value per share.
And if we want to see if a REIT is growing intrinsic value?
We see if they are growing adjusted funds from operations per share.
AFFO per share is the ultimate metric for REITs.
Let’s filter out all REITs that do not have positive AFFO per share growth over the past 7 years AND filter out any REIT not projected to grow AFFO per share at least 3% annually moving forward.
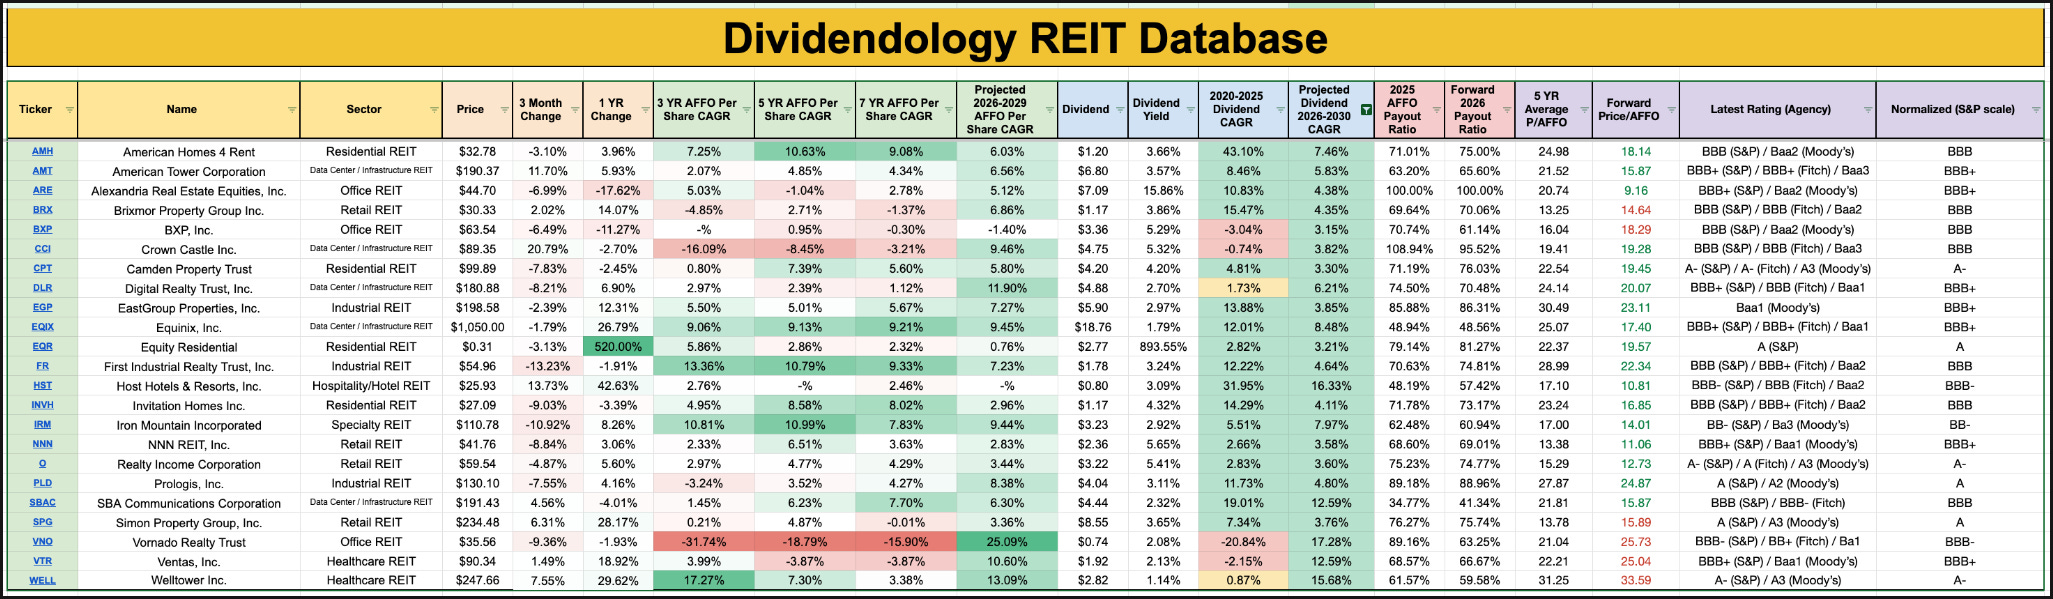
All of a sudden, we went from 33 REITs down to 23.
💸 2. Growing Dividends
The majority of people investing in REITs are buying them for their high yields.
So naturally, we need to make sure those dividends are sustainable.
Let’s filter out all REITs that have a forward AFFO payout ratio of above 80% AND a yield of at least 3%.
Now, we are left with just 15 REITs.

📑 3. Balance Sheet Health
Finally, we must assess the health of the REITs balance sheet.
In reality, this would require analyzing things like:
Total debt vs. market cap
Secured vs. unsecured debt
Fixed-rate vs. variable-rate mix
Weighted average interest rate
Debt ladder
Leverage ratios
These are things I discuss in my 46 minute video on how to analyze REITs.
But since we’re simply running screens, we will use our credit ratings.
If we remove any REIT with a normalized credit rating of BB- or below, we are still left with 15 REITs.
💥 4. Valuation
The last thing to assess?
Valuation.
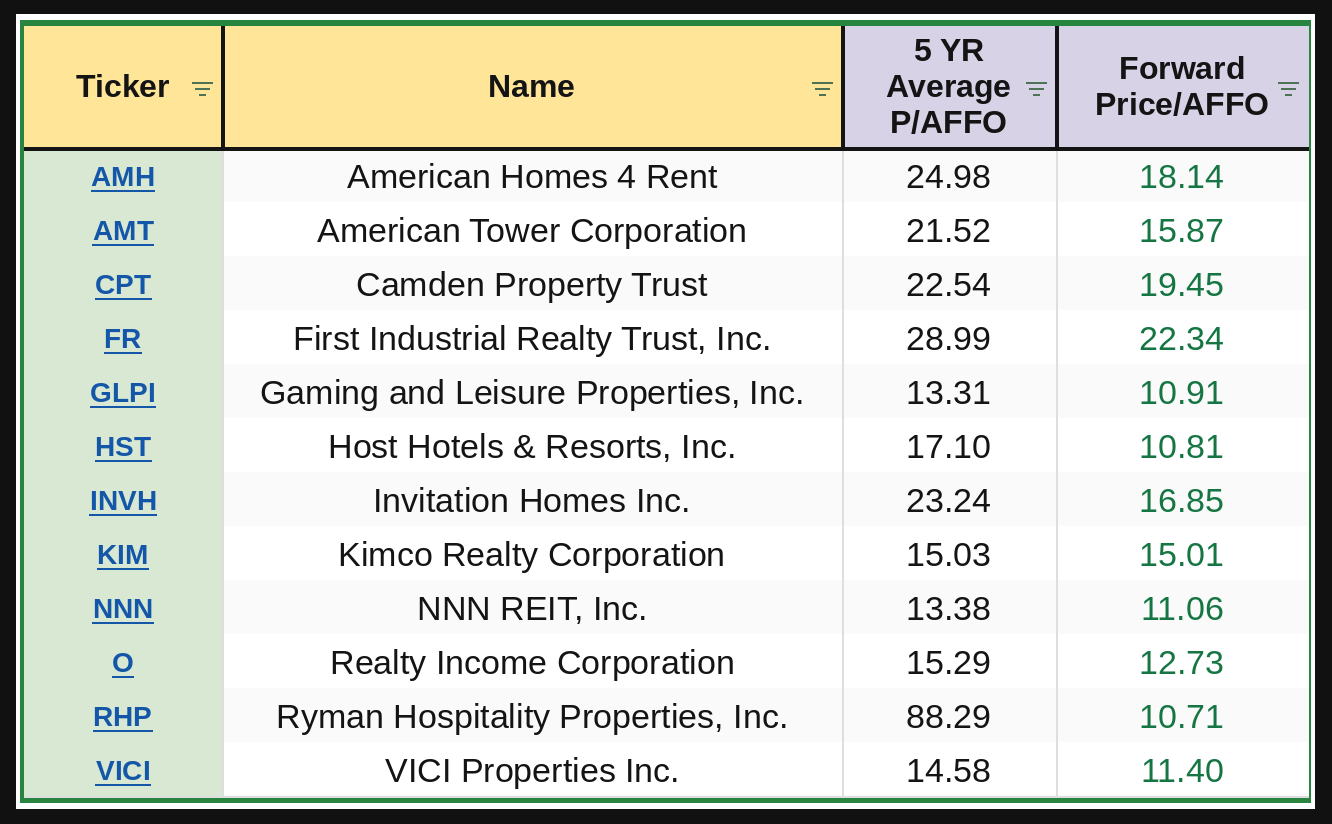
Valuations have compressed so much that 12 of the 15 REITs that made it this far are trading below their historical multiples!
Obviously there is more to assess when it comes to valuations, and the rate at which they can grow AFFO per share in the future heavily impacts the multiple that REITs deserve to trade at.
But with that being said…
It’s clear valuations are vastly more attractive now than they have historically been.
If we look at the most popular REIT on our list (Realty Income), we can see they are essentially trading at their lowest P/AFFO Per Share multiple in the last 5 years.
Current P/AFFO Per Share: 12.73x
5 Year Average P/AFFO Per Share: 15.29xx

With the help of the Dividendology Database, we were able to quickly spot where some of the best potential opportunities in the REIT market are by creating an investable universe.
Creating an investable universe removes roughly 80% of the work required.
As AI continues to erode the MOAT of many technology companies, real assets like REITs, MLPs, and energy stocks will continue to grow in value.
This is why there is such a need for the Dividendology Database-
And it’s why I’m excited to share that I’m working on a VERY important project-
An MLP/Midstream Database for members of Dividendology.
Midstream stocks have been some of the most compelling high yield investments over the last 5 years.
So much so, that the midstream ETF, AMLP, has basically doubled the performance of the tech heavy S&P 500 over the last 5 years.
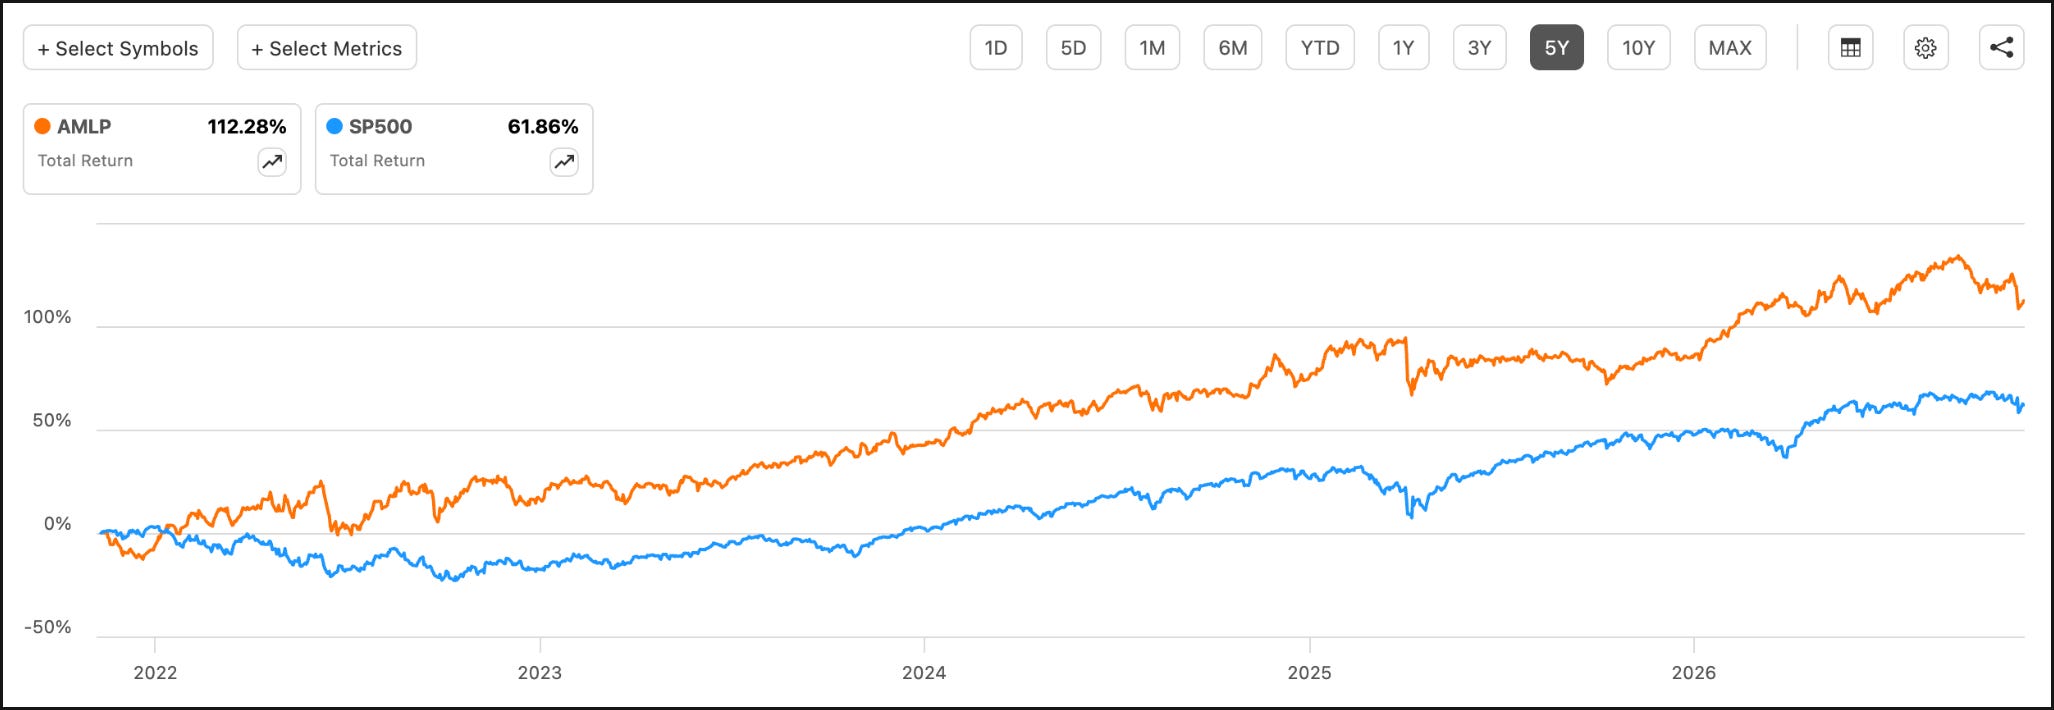
Even after this run in share price, there are some incredible high yield opportunities in the midstream space.
In fact, some of the biggest winners in our High Yield Portfolio this year have been midstream companies.
Did you know Midstream companies have an advantage over REITs and BDCs?
Here’s why:
No 90% payout requirement. REITs and BDCs are required to pay out by law 90% of their taxable earnings. Midstream companies have no equivalent industry-wide requirement.
More room to fund growth internally. As a result of the above, Midstream operators can retain more cash to build or expand pipelines, pay down debt, or buy back shares. That can reduce their need to issue stock or borrow to fund growth.
A bigger cushion for the payout. Some midstream operators generate substantially more cash than they distribute, giving them room to absorb a weaker quarter or fund new projects while maintaining the payout.
The goal of the database will be to help us identify some of the best opportunities in the Midstream space-
And have access to the data that is incredibly difficult to get that most softwares don’t cover for this asset class.
We are targeting a release date for this Midstream Database of November 23rd.
If you want to get access to the Dividendology Database and the new release, as well as all the features mentioned below, you can do so here:
See you soon!
Dividendology
Check out these resources:
Tickerdata 🚀 (My automated spreadsheets and instant stock data for Google Sheets!)
Interactive Brokers 💰 (My favorite place to buy and sell stocks all around the world!)
Seeking Alpha 🔥 ($30 off! + 7 day free trial)
The 7.3% implied cap rate looks cheap next to the 6.4% median, but the yardstick moved. Over the last 15 years the 10-year Treasury averaged about 2.6%, so a median cap rate gave REITs roughly 3.8 points over bonds. Today the 10-year sits at 5.0%, which leaves 7.3% only 2.3 points above it. Measured against Treasuries, REITs are pricier than usual, not cheaper.
That changes what the trade depends on. For cap rates to drift back toward 6.4% without the spread to bonds getting even thinner, the 10-year has to come down a lot. And the macro isn't helping: we're nine months into a stretch where growth and inflation both run hot, and the market is pricing Fed hikes, not cuts.
So I'd read the 5th percentile valuation as mostly a rate story. Picking the good REITs inside the universe still matters, but a sector-wide rerating probaly waits for the bond market.
Really enjoyed this one. I loved how you built the investable universe step by step, going from 33 REITs down to 15. The way REITs are sitting near the 5th percentile on valuation made the opportunity really clear. Thank you.